
Copay and Coinsurance
Copay and coinsurance are two types of costs you have to pay for healthcare services.
Copay vs. Coinsurance
What's the difference?
Both terms are what insurance companies call cost sharing. More simply, it's the share of medical expenses you're expected to pay.
A copayment is a specific dollar amount you're usually asked to pay at the time you receive health care services. An office visit to the family doctor will have a copay.
Coinsurance is a percentage of the allowed charges. Because coinsurance is a percentage of the bill, it's often much higher than a copay, especially for expensive services.
Copay
This is a fixed amount you pay for a covered health care service. Usually you're asked to pay it when you get the service.
The amount can vary by the type of covered health care service.
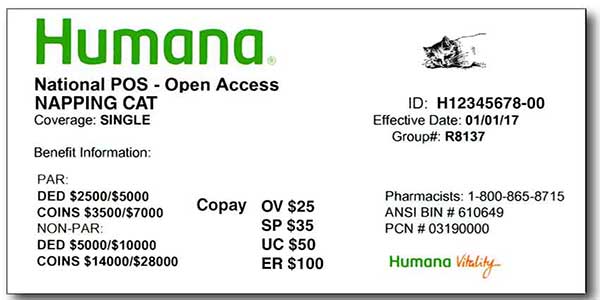
The copay amount will often be listed on your insurance card. Depending on your plan, it may read:
| Service | Copay |
|---|---|
| Office Visit (OV) | $25 |
| Specialist Office Visit (SP OV) | $35 |
| Urgent Care (UC) | $50 |
| Emergency Room (ER) | $100 |
• Keep in mind, many plans today no longer charge a simple ER copay. Instead, the ER visit goes toward your deductible, and then you pay coinsurance.
You'll also have a copay when you get a prescription filled.
Generic drugs have the lowest copay, and non-preferred brand drugs the highest.
♦ One of the results of the Affordable Care Act was that after 2014, copays for in-network covered services count toward the out-of-pocket maximum.
However, they don't have to count toward the deductible.
• Copays almost never count toward your deductible. Instead, copays are typically used in place of a deductible for specific services (like a standard office visit), or they apply after the deductible is met. It's rare for a copay payment to reduce your deductible balance.
Check your plan's benefits description or call the customer service number on your insurance card to be sure.
• Some plans limit the number of office visits or treatments at a specific copay. After that number is reached, these plans usually apply the charges to the deductible.
This can become costly if you need more visits than the plan allows.
• This limitation also discourages people from seeking care when they should, because they're afraid of going over their limit.
Fortunately, most health plans must now cover a set of preventive services, like shots, physical exams and screening tests, at no cost to you.
This includes plans available through the Health Insurance Marketplace.
♦ For some services, you may have both a copay and coinsurance.
Example
You visit a pulmonologist (lung specialist).
You'll have a specialist office visit copay.
You could have a separate charge for any breathing tests they give you, since these aren't preventive. The coinsurance for the test usually kicks in only after you've met your annual deductible.
If you haven't met the deductible, you'll likely owe the full allowed amount for that test, not just a coinsurance percentage.
♦ The charges you receive depend on how the bill is submitted to the insurance company, and on the contract your plan has with providers.
Unfortunately, you won't find this out until you receive an Explanation of Benefits (EOB).
♦ When choosing a new plan, think about how often you visit a doctor or take expensive drugs. If it's often, you might want a plan with low copays.
Coinsurance
Coinsurance is usually a percentage of the allowed charges (for example, 20%).
• You usually pay the percentage after first paying your deductible.
This shouldn't be confused with the term copayment.
• A copayment is a fixed amount (for example, $25 for an office visit).
Plans vary greatly in which services require coinsurance, so you need to read your plan's documents carefully.
Plans with both in-network and out-of-network benefits usually have a lower coinsurance percentage for in-network providers than out-of-network ones.
It's common to have 20% to 30% coinsurance.
Example
• Your insurance allowed $1,000 for a special test, and you've already met your deductible. Your coinsurance payment of 20% would be $200.
• Your insurance would pay the rest of the allowed amount, $800.
Keep in mind, the amounts you pay as coinsurance count toward reaching your out-of-pocket maximum.
♦ Once you reach your plan's out-of-pocket maximum, you stop paying coinsurance and the plan pays 100%.
When you choose a health insurance plan, it's important to understand what your insurance company covers and what it requires you to pay as coinsurance.
As a rule, the lower the coinsurance percentage, the higher the plan's monthly premium.
♦ If your income is between 100% and 250% of the federal poverty level and you buy a Silver plan through the Marketplace, you may qualify for Cost-Sharing Reductions (CSR).
CSR modifies the health plan itself to lower your out-of-pocket costs (deductibles, copays and coinsurance) and lowers your out-of-pocket maximum.
♦ It's important to see if you qualify for CSR.
Cost-Sharing Reductions are sometimes confused with the term "Out-of-Pocket Savings." "Out-of-Pocket Savings" is just the Marketplace's consumer-friendly label for CSRs.
If you qualify for Cost-Sharing Reductions, you'll receive Out-of-Pocket Savings. Thank our elected officials for cooking up these phrases.
Read how Out-of-Pocket Savings and Cost-Sharing Reductions can work for you.
